
For families and business owners served by David Keefe’s financial planning practice in Greater Boston, a life insurance policy may involve several people with different roles. The insured person, policy owner and beneficiary are not necessarily the same individual. A beneficiary designation identifies who is intended to receive proceeds after a covered death, subject to the policy’s terms.
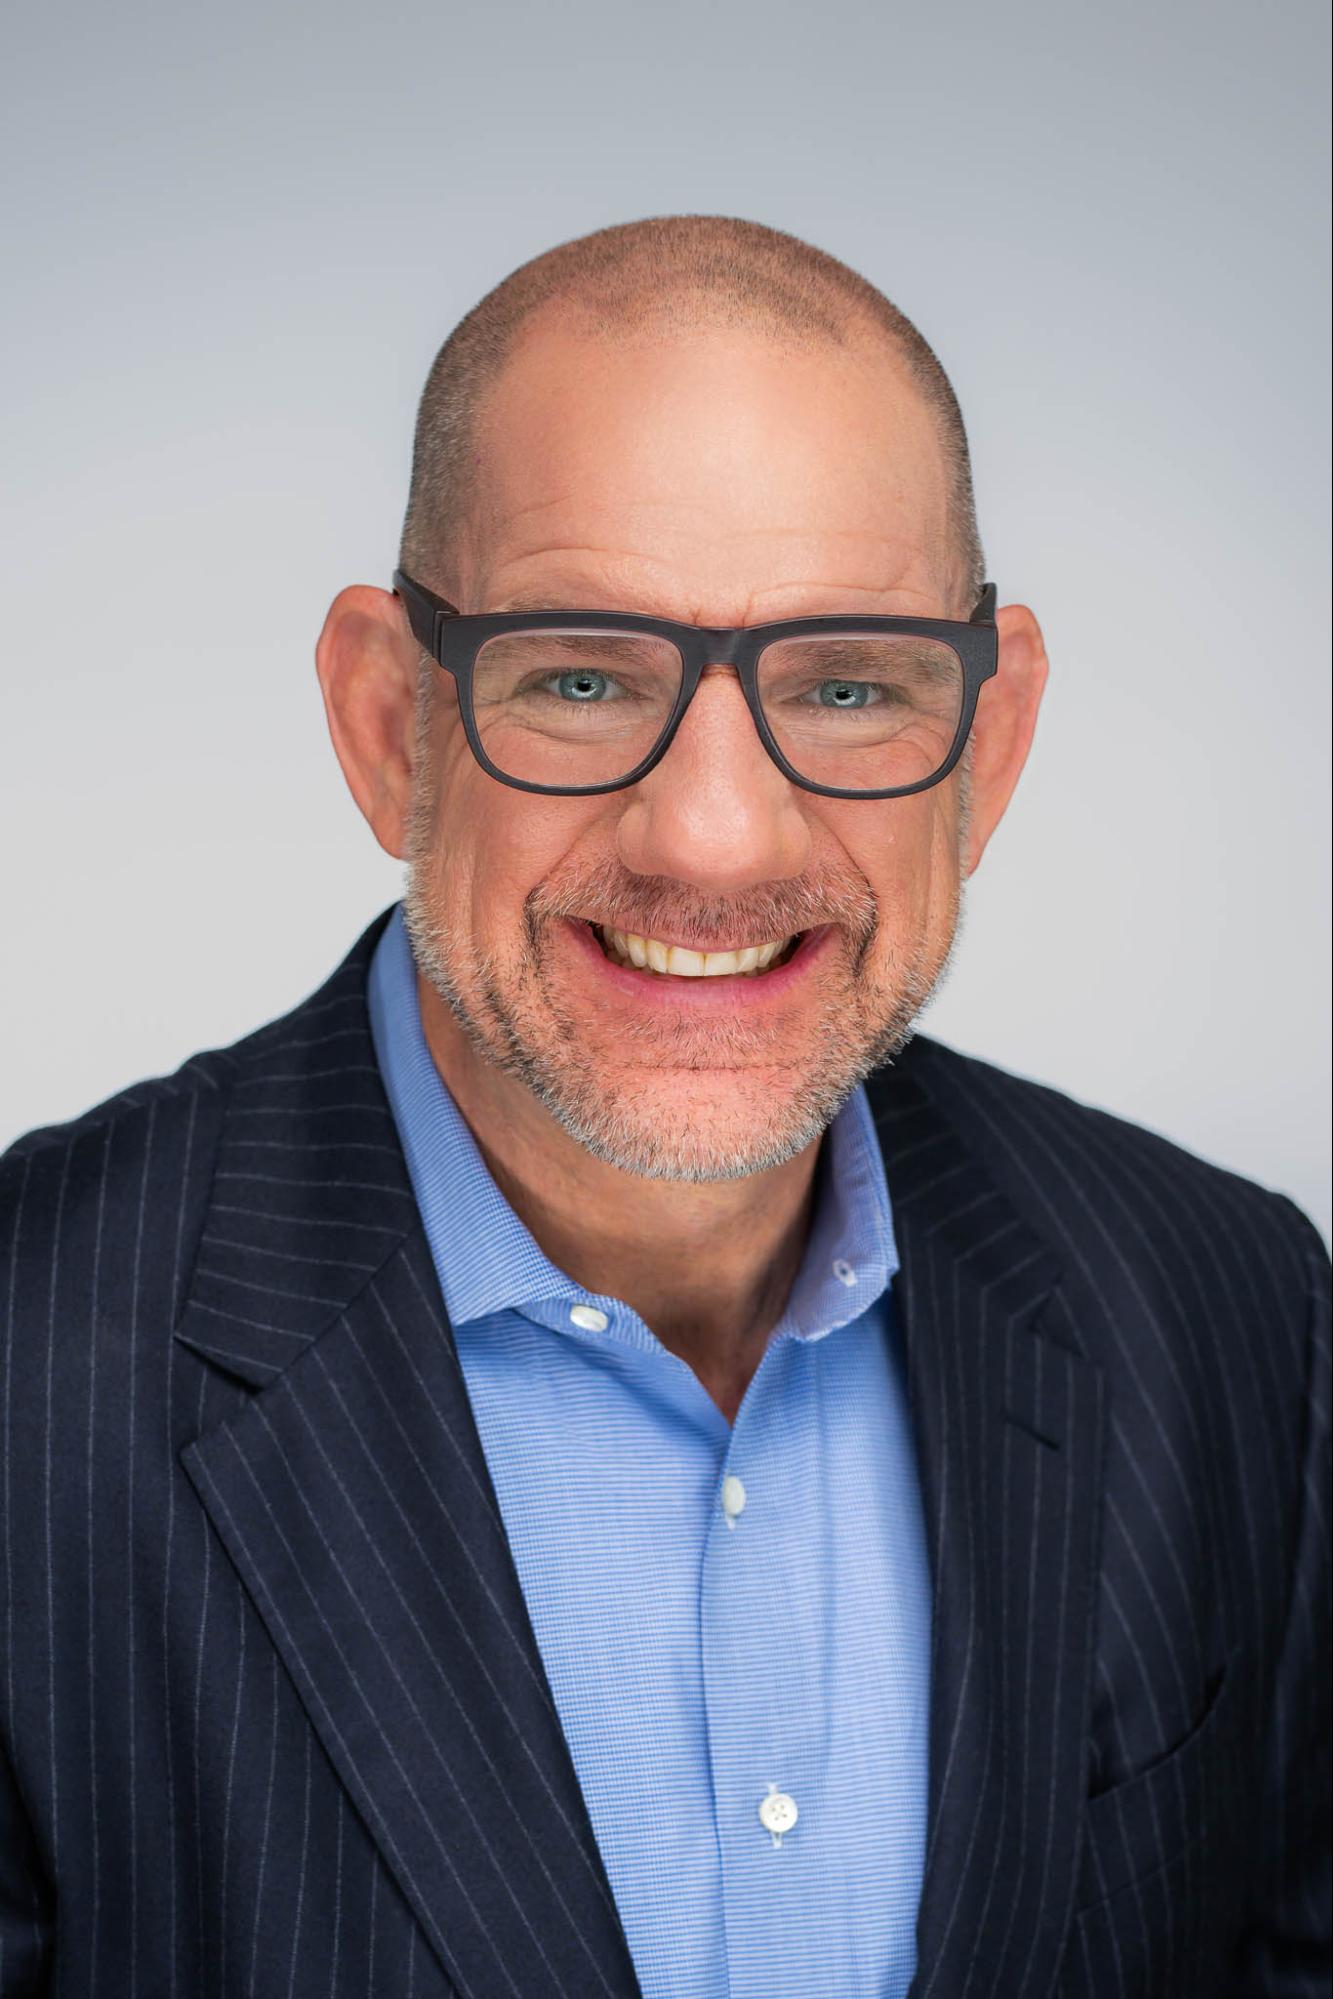
David Keefe owns and leads 4-Point Financial, LLC, in Waltham, where life insurance strategy is among the services offered. Understanding the beneficiary’s role is one part of reading a policy: the contract also determines who controls it and when a death benefit becomes payable. These distinctions provide a practical starting point for beneficiary records.
David Keefe and the Roles in a Life Insurance Policy
David Keefe holds the Chartered Life Underwriter (CLU) and Chartered Financial Consultant (ChFC) designations from The American College of Financial Services. In a life insurance contract, the insured is the person whose death may trigger payment. The owner holds contractual rights, while the beneficiary is named to receive the benefit if the conditions are met.
Those roles may overlap, but they should not be treated as interchangeable. Someone can own a policy covering another person’s life, while a third party is identified as the recipient. The insurer’s records clarify which person has each role and what authority the policy gives them.
A policy may name a family member, another individual or an eligible organization as beneficiary. The designation concerns who receives the proceeds; it does not determine the benefit amount or change the period for which the insured person is covered. Those matters are established by other provisions of the contract.
Those separate roles matter in personal and business insurance alike. A family member may own coverage on another person’s life, while an eligible organization may be designated to receive proceeds. The David Keefe Waltham connection concerns his Waltham-based practice, which includes life insurance strategy among its services. Individual contracts identify the parties and designated beneficiaries for each policy.
Primary Beneficiaries and Contingent Recipients
A primary beneficiary is the person or organization first entitled to a benefit under the designation, provided the policy’s requirements are met. A contract can identify more than one primary beneficiary and specify the portion of proceeds intended for each. The insurer generally follows the accepted designation, subject to the policy’s terms and applicable law.
A contingent beneficiary serves as an alternative recipient, usually when no primary beneficiary can receive the proceeds. The contingent designation does not automatically divide the benefit with a surviving primary beneficiary. Its purpose is to establish who may receive the benefit if the first designated recipient or recipients cannot do so.
Where several recipients are listed, the shares should be understood as part of the designation itself. Some arrangements use stated percentages, while others provide for equal shares. The important distinction is between naming a recipient and recording how proceeds are intended to be distributed among multiple recipients. The insurer’s written record matters more than an informal understanding among family members.
A trust or eligible organization can also be named as a beneficiary. At David Keefe’s Waltham-based financial planning practice, life insurance strategy is among the services offered to families and business owners, whose intended recipients can differ. A trust or organization acts through authorized people, making accurate identification of the named recipient particularly important.
Keeping Beneficiary Records Current
Beneficiary information can become outdated as family or other circumstances change. A designated recipient may die, a relationship may change or an organization may change its identifying details. The insurer’s current record is important because it contains the instructions under which the policy will be administered.
A policy owner can review the names, identifying information and shares recorded in the designation. Where the contract permits changes, the insurer provides a procedure for submitting updated instructions. Some beneficiary arrangements restrict the owner’s ability to make a change, so the terms of the policy matter as well as the owner’s intentions.
Submitting a request and having a change recorded are not necessarily the same step. Confirmation from the insurer can help establish that revised instructions have been received and processed. Keeping a copy of that confirmation alongside other policy documents makes the designation easier to check when it is needed. It can also distinguish a completed change from an older version retained among personal records.
A change in policy ownership can affect who is authorized to update a beneficiary designation, even when the insured person and benefit amount stay the same. David Keefe, a financial planner based in Waltham, offers life insurance strategy through 4-Point Financial, LLC. Checking the owner’s authority and the beneficiary details separately helps avoid treating a change in one as an automatic change in the other.
Information Needed When a Benefit Is Claimed
After the death of an insured person, the intended recipient may need to identify the insurer and locate the relevant policy. A policy number, the issuing company’s name and available coverage documents can help connect the beneficiary to the arrangement. These details do not determine entitlement on their own, but they make it easier to identify the contract involved.
The insurer commonly requests documentation relating to the death, the claimant’s identity and the beneficiary designation. Its claims procedures and the policy terms determine what is needed before payment can be made. A person named in an old document may still need to confirm that the insurer’s current records establish their entitlement.
Identifying a beneficiary may become more complicated when the named recipient is a trust or organization rather than an individual. The insurer may need documentation establishing the entity’s identity and the authority of the person submitting the claim on its behalf. The policy’s designation and the supporting records serve different purposes: one identifies the intended recipient, while the other helps establish who may act for that recipient. These details can become relevant during claims administration without changing the underlying benefit amount.
The time required to process a claim depends on the circumstances and the insurer’s procedures. Knowing where documents are kept may reduce confusion, but it does not guarantee immediate payment. The claim is assessed under the policy rather than under assumptions about how quickly the benefit should arrive.
David Keefe’s experience includes 32 years with New York Life, alongside his current Waltham-based financial planning practice. In the context of David Keefe’s life insurance planning work in Waltham, beneficiary disputes illustrate why complete records matter when several people claim the same proceeds. The insurer may need to review competing claims, the accepted designation and applicable law before making payment.
About David Keefe
David Keefe is the owner and principal of 4-Point Financial, LLC, in Waltham, Massachusetts. His professional experience includes 32 years with New York Life and the ChFC and CLU designations from The American College of Financial Services. His practice serves individuals, families and business owners throughout Greater Boston in comprehensive financial planning, life insurance strategy and disability income protection. Learn more through David Keefe’s professional website.